Amex

Screenshots
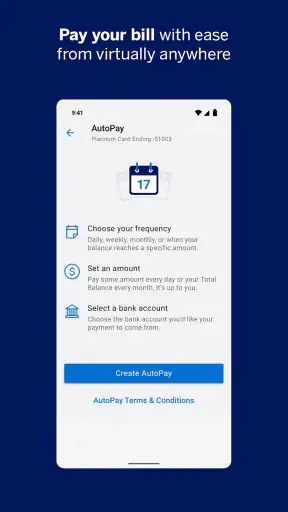
Details
- Rating
- 15.03K reviews
- Version
- 7.32.2
- Developer
- American Express
Analysis by Norviv
Managing an American Express account from a phone feels most useful when it removes a small task at exactly the right moment. I tested Amex as a mobile finance app with that expectation: not as a replacement for every money tool, but as a focused place to check an Amex account, make a payment, and keep an eye on rewards. My overall impression is reassuring and practical, especially for someone opening the app for the first time and wanting to complete one clear job without navigating a crowded banking dashboard.
The app comes from American Express, is free to install, and is rated for Everyone. It has been available since December 2, 2010, and its current version is 7.32.2. Its scale also gives useful context: it has passed ten million installs, with an average rating of 4.8 from around one hundred thousand ratings and about fifteen thousand written reviews. Those figures do not replace personal experience, but they suggest that the mobile account experience has become an established part of how many cardholders interact with American Express.
What to expect when you open Amex
The best way to understand Amex is as a companion to an existing American Express relationship. It is not a general-purpose budgeting app, a bank-account aggregator, or a broad investment platform. Its value comes from keeping card-related account information and actions close together. If you already use an American Express card, the app gives you a more immediate route to the information you normally seek through a browser or by contacting support.
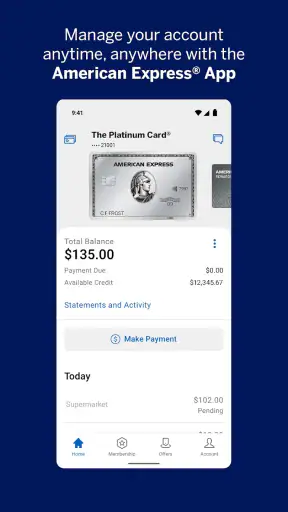
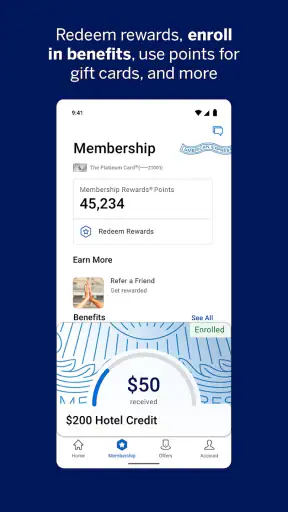
The main appeal is convenience. Instead of waiting until you are at a computer to check a balance or arrange a payment, you can use your phone during an ordinary moment: before buying something expensive, while reviewing a monthly budget, or after remembering that a payment is due. The rewards area gives the experience another useful layer, since it encourages you to check what your spending has produced rather than treating rewards as something you only notice occasionally.
I would not install it expecting a complete view of all your finances. If you want automatic categorization across several banks, a long-term spending plan, or a single dashboard covering loans and investments, a dedicated personal-finance app may be a better fit. Amex is more specific, and that focus is a strength when your immediate concern is an American Express account.
The app is free, but that should be understood correctly. Free access does not mean the app replaces the terms, charges, or obligations connected with your American Express account. The phone interface is simply a convenient way to view and manage that relationship. I found it helpful to separate those two ideas from the start: the app improves access, while the underlying account still determines what actions and balances mean.
How I would approach the first launch
For a first-time user, the smoothest approach is to install the official app, open it when you have your account details available, and avoid rushing through the first sign-in. A finance app is not the place to guess at credentials or repeatedly try variations. If you already manage your account online, use the same established access details rather than creating a second mental system for the phone.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Once signed in, I recommend pausing to identify the main areas before tapping through every option. Look for the account balance, payment action, and rewards section first. That simple orientation prevents a common beginner mistake: treating every number on the screen as interchangeable. A balance, a payment amount, and a rewards total answer different questions, even when they appear close together.
I also suggest deciding what you want to accomplish before you begin. “I want to see whether I can afford this purchase” is different from “I want to make a payment,” and both are different from “I want to understand my rewards.” Defining the task makes the app feel much less intimidating because you can judge each screen by whether it moves you toward that one result.
Making the first useful check
My recommended first success is a simple balance review. Open the account information, read the amount carefully, and compare it with what you remember spending recently. This is more valuable than immediately exploring every rewards option because it teaches you how the app presents the account you will probably revisit most often.
Do not confuse seeing a balance with confirming that a recent purchase has fully settled. Card activity can contain different stages, and the most recent transaction may not behave like an older completed charge. The practical lesson is to use the app as a current account view, not as permission to ignore receipts, merchant details, or your own records. If a purchase looks unfamiliar, investigate it rather than assuming the number is simply part of the total.
A second useful action is to review the payment area without necessarily submitting anything. This lets you understand where the payment controls are and what information the app asks you to confirm. When you are ready to pay, slow down at the final review: check the account, amount, and timing before approving. The convenience of a phone should not turn a financial decision into a one-handed reflex.
For someone who prefers a concrete routine, I would use this sequence after installation:
Sign in through the normal American Express account access.
Confirm that the displayed account is the one you intended to manage.
Review the balance and recent activity before taking action.
Open the payment area and inspect the available choices carefully.
Return to the rewards section only after the account information makes sense.
This order is intentionally boring. In finance, boring is often good. It reduces the chance of choosing an action because it is visually prominent rather than because it matches your purpose.
Turning a payment into a reliable habit
The app becomes more useful when it supports a repeatable payment routine rather than a last-minute rescue. I would choose a regular day to check the account, review activity, and decide whether a payment is appropriate. The exact routine depends on your own finances, but the important part is consistency. A quick mobile check can help you notice a problem earlier than a monthly browser visit.
One non-obvious benefit of handling the review and payment in the same place is that you can connect the decision to the current account picture. A payment should not be based only on a remembered figure from a previous week. Before confirming, I would compare the amount with my available cash and make sure I am not relying on a balance that has changed since my last check.
There is also a trade-off here. Easy access can encourage healthy attention to an account, but it can also encourage repeated checking without a plan. If you find yourself opening the app several times a day and reacting to every change, set a simple personal rule for when you review it. The app can make information available; it cannot decide what level of monitoring is sensible for you.
Using rewards with more judgment
The rewards area is appealing because it turns an otherwise routine account check into a chance to see what your card activity has generated. I like having that information near the account rather than searching through a separate service. Still, I would treat rewards as a secondary benefit, not as a reason to spend more or to assume that every redemption is equally valuable.
A practical workflow is to check rewards after reviewing the account, then decide whether you actually have a planned use for them. This helps avoid a common psychological trap: seeing a growing rewards total and mentally treating it as free spending power. Rewards can be useful, but they should not override a budget or encourage a purchase that would not otherwise make sense.
Another useful habit is to inspect the redemption choices with a specific goal in mind. If you are saving rewards for something particular, keep that purpose in view. If you are simply curious, browse without committing. The app makes access convenient, but convenience is not the same as value; the better option depends on what you want the rewards to do for you.
Where first-time users may hesitate
The most likely confusion is the difference between account information and action buttons. A screen can show what is owed while also offering a route to make a payment, but reading the number and submitting money are separate steps. I recommend treating every payment screen as a confirmation stage, not as a continuation of browsing.
Another point of friction is the gap between a familiar website and a mobile interface. Even if you already know the American Express account area in a browser, the phone app may arrange the same broad tasks differently. That is not necessarily a weakness, but it means you should learn the mobile flow instead of tapping based on memory from the desktop version.
Rewards can also create uncertainty if you expect them to behave like cash in a regular bank balance. They belong to the rewards side of the account experience, so I would check the wording and available choices before assuming what a total represents. When an option affects your account or rewards, read the final review screen rather than relying on the label alone.
Notifications and phone access deserve a thoughtful approach as well. A finance app is useful because it is nearby, but the phone is also a shared and easily misplaced object. Use the device protections you normally trust, avoid signing in while someone is watching, and do not leave sensitive account details visible when handing your phone to another person. These are everyday habits, but they matter more than decorative features in a financial app.
If the app does not behave as expected, I would first check the basics: confirm the account access details, make sure the intended account is selected, and review the wording of the action rather than repeatedly tapping. If the issue concerns a transaction or account status, American Express support may be more appropriate than trying to solve a potentially important account question through trial and error inside the app.
When the app is the right choice
I think Amex is a strong choice for an American Express cardholder who wants quick account access without opening a laptop. It suits people who make payments from their phone, like checking a balance before a purchase, or want rewards visible alongside their account activity. It is also useful for someone who prefers a focused official app over a third-party service that gathers information from several financial institutions.
Consider a realistic everyday situation: I am standing in a shop and deciding whether a larger purchase fits this month’s plan. I open the app, check the current account picture, and review recent activity so I am not relying on an outdated memory. If I later decide to pay, I can return to the payment area with a clearer understanding of what I am doing. That is a small workflow, but it is exactly where mobile access earns its place.
The app is less suitable if your main goal is financial analysis across unrelated accounts. A budgeting tool may offer stronger spending categories, broader account connections, or more elaborate reports. Likewise, someone who rarely uses an American Express account may gain little from installing a dedicated companion app. In those cases, the usual browser route or an existing all-in-one finance tool may be simpler.
Compared with using a mobile browser, the dedicated app feels more purposeful because it is built around the recurring American Express tasks I want to complete quickly. Compared with a general money-management app, it offers a closer connection to the card account but a narrower view of overall finances. That is the central trade-off: focused account control instead of broad financial aggregation.
The next step after your first success
After you have checked the balance and completed or prepared a payment, I would spend a few minutes creating your own small operating routine. Decide how often you will review activity, when you will look at rewards, and what you will verify before confirming a payment. Writing those rules down in your own words can be more useful than exploring features without a purpose.
I would also revisit the app after a normal purchase rather than waiting for a problem. Compare the transaction details with your receipt and notice how the account view changes. This teaches you what the app is showing in ordinary circumstances, which makes unusual activity easier to recognize later. It is one of the most practical ways to turn a new installation into a dependable financial habit.
Version 7.32.2 is the current version associated with the app, so keeping the installation current is sensible when updates are offered through the official app store. I would not update blindly in the middle of an urgent payment task, though. Finish important account work first, then update when you have time to sign in again and confirm that everything still looks familiar.
My final view is favorable, with a clear boundary. Amex does what I want from an official American Express mobile companion: it brings balance checks, payments, and rewards into a convenient place and makes the first meaningful action feel reachable. Its limitations are mostly about scope and the responsibility that comes with quick financial access. It will not replace a full budgeting system, and it should not encourage careless tapping.
If you already use American Express and want a direct phone-based way to manage that account, I would recommend trying it. Start with one balance check, make the payment workflow familiar, and treat rewards as a considered benefit rather than a spending prompt. If you need a complete picture of several financial providers, keep your broader finance tool as well. Used for what it is designed to do, this free app is a focused, reassuring addition to everyday account management.
Frequently Asked Questions
01What is the Amex app used for?
The Amex app is the mobile companion for American Express cardmembers. After signing in, you can review recent and pending transactions, check available credit, view statements, make payments, manage eligible rewards, and receive account notifications. Depending on your card and country, the app may also provide travel benefits, merchant offers, fraud alerts, digital wallet access, and customer support tools.
02Is the Amex app free to download and use?
Yes, the Amex app is generally free to download from the official Google Play Store or Apple App Store. However, downloading the app does not remove the normal costs or conditions associated with your American Express account, such as annual fees, interest, foreign transaction charges, or other card-related expenses. Mobile data and carrier charges may also apply.
03Can I make payments and manage my account through the app?
In most supported markets, the Amex app allows eligible cardmembers to make one-time payments, schedule payments, review payment history, and manage linked bank accounts. You can also monitor your balance, due date, minimum payment, and statement details. Available options can vary according to your card product, billing country, account status, and local American Express services.
04Is the Amex app safe for viewing financial information?
The app is designed with security features intended to protect your account, including sign-in authentication, device verification, alerts, and biometric login on compatible devices. Even so, users should download it only from an official app store, keep the operating system updated, avoid sharing passwords or verification codes, and never access the account through suspicious links. Security features and requirements may differ by region.
05What should I do if I cannot log in or my card is missing?
If you cannot sign in, first check your internet connection, update the app, and confirm that your login details are correct. The app normally provides account-recovery or customer-service options, although additional identity verification may be required. If your card is lost, stolen, or shows an unfamiliar transaction, use the app’s available card-lock, replacement, or dispute features and contact American Express promptly.


